By Frank Hornung and Sergey Klimov
When Microsoft moved to the Seattle area in 1979, joining well-established Pacific Northwest companies such as Boeing (aerospace) and Weyerhaeuser (timberland), it set off an enduring tech boom. Fifteen years later, when Jeff Bezos was starting his online bookstore that eventually became Amazon, he chose Seattle for its abundance of tech talent.
Today, Microsoft and Amazon together employ almost 100,000 people, Zillow and Expedia are both headquartered in the metro area, and Google, Meta, Apple and Oracle all have major outposts there. This critical mass of tech companies is one reason that the Seattle area is at the forefront of cloud computing, AI, gaming and software as a service. Companies like OpenAI, NVIDIA and SpaceX all expanded local operations in 2025.
But Seattle is no longer just a tech center. Businesses like Starbucks, Costco, Nordstrom and Alaska Airlines are also Seattle-based, and healthcare, education, business services and government have become powerful growth engines. Because the Seattle economy has diversified and matured, it is a natural choice for multifamily investors looking for dependable, long-term returns.
While some companies have reduced downtown office space or expanded into nearby submarkets, there has not been a broad corporate exodus from the Puget Sound region. For downtown Seattle, the story is increasingly about residential and lifestyle recovery rather than office utilization alone.
Residential population is rising, up 53 percent over the past decade. Waterfront traffic and tourism are improving, stadium district activity remains strong, and expanding light rail connectivity continues to enhance downtown accessibility.
Multifamily demand has remained resilient as renters still value walkability, transit access and urban amenities, while high homeownership costs keep many residents in the renter pool longer.
Supply, Demand in Relative Equilibrium
Another virtue of the Seattle multifamily market is that supply never gets too far ahead of demand. For better or worse, developing new multifamily units is more complex and costly than in other markets. Long permitting cycles and evolving regulations — especially in Seattle and greater King County — add time and cost to projects, but they also make rapid supply surges virtually impossible.
Regional unit deliveries peaked in the first quarter of 2024 and have decreased in each quarter since then. Throughout 2025, more than 12,000 units were added to the metro area’s inventory, according to CoStar data, with nearly 16,000 units in the pipeline.
By far, the highest number of completions was in King County, most notably the 623-unit Eastline Grand in Redmond, the 550-unit Verdant Apartments in Shoreline and the 506-unit Museum House in Seattle.
Although employment declined slightly in 2025, apartment demand closely shadowed supply, with absorption totaling 12,100 units across the area. In some Seattle neighborhoods like South Lake Union and Queen Anne, leasing outpaced deliveries.
An important reason for this sustained demand is that buying a home is challenging, even for Seattle’s well-compensated workforce. According to Axios, the cost of ownership in Seattle is 50 percent higher than the cost of renting.
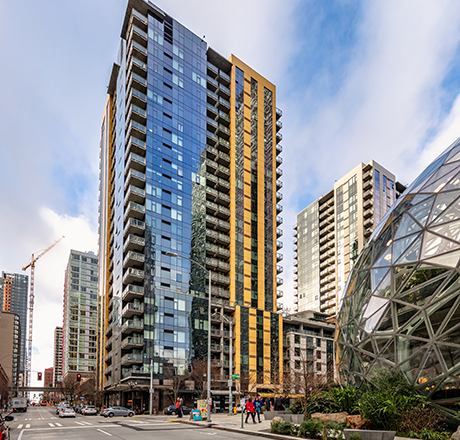
Seattle developers tailor their offerings accordingly. Noting the prevalence of high-income Seattleites priced out of ownership, developers in the Seattle area focus primarily on luxury, Class A units. The 33-story Museum House, which opened in March 2025, is a case in point. The development features a rooftop pool, gym and an enclosed skybridge connecting its twin towers. Proximity to transit has also guided development. For instance, the Verdant is steps away from the Shoreline South/148th Link light rail station.
Market Prognosis: Good and Getting Better
The greater Seattle multifamily market has remained in a holding pattern in recent quarters, with modest softness following the recent construction peak. Vacancy rose 10 basis points between the second quarters of 2025 and 2026 to 7.3 percent, slightly above the 6.8 percent U.S. average, according to Moody’s Analytics. Rent growth increased by 0.4 percent year over year, slightly outperforming the national average, which was essentially flat.
The outlook is expected to improve significantly in 2027 as deliveries are forecast to drop by nearly 50 percent. Landlord-provided concessions in Seattle submarkets like Capitol Hill and the University District, which had seen significant supply pressure, are likely to be discontinued. Rent growth remains soft in downtown Seattle, where about the same number of new units will open this year as last year. Bothell, a city of 50,000 north of Bellevue, Shoreline, Marysville and Monroe in Snohomish County have the highest number of units under construction.
While oversupply is on the wane, demand is expected to rise in 2026. Employment is forecast to tick up this year, especially as local tech firms search nationwide for AI experts.
In 2027, absorption is projected to outpace deliveries for the first time since the COVID-19 pandemic, and asking rents are expected to increase by 3.1 percent in the Seattle market compared with 2.4 percent for the U.S. on average.
Investment Sales Activity Surges
Investors are taking note of Seattle’s evolving supply-and-demand dynamics. Multifamily sales in greater Seattle hit $6.3 billion in 2025, marking a 48 percent year-over-year increase from 2024 — and its highest total since 2021, according to MSCI.
The largest individual sales in the past 12 months were both in Seattle proper. Weidner Apartment Homes purchased the 654-unit Via6 Apartments for $295 million, while PCCP and Timberline Partners acquired the 532-unit Jackson Apartments from Vulcan Real Estate for $173 million.
Security Properties also purchased a five-asset portfolio from Washington Holdings totaling 903 units in Seattle and Redmond for $401 million. Overall, Seattle’s 12-month rolling cap rates have compressed slightly over the past two years from 5.48 to 4.86 percent as of the second quarter of 2026.
The consensus view among these investors is that Seattle has the ingredients that matter most over the long term. This includes population growth, expensive for-sale housing, real barriers to new supply and enduring renter demand.
This is one reason Seattle moved into the top 10 — ranking ninth — in CBRE’s 2026 North American Investor Intentions Survey, up from 11th place the prior year.
Frank Hornung is a senior director of loan originations at Lument, where he is responsible for originating Fannie Mae, Freddie Mac, FHA, bridge and CMBS loans for multifamily clients in the Pacific Northwest. Sergey Klimov is a director at Lument and is based in Seattle. He specializes in originating and structuring small multifamily loans on a national basis.